Ethical Finance Needs an Outcome Ledger
What Islamic finance and impact investing can learn from each other


What Islamic finance and impact investing can learn from each other
 68
 0
After the flood, recovery capital must do more than replace what was lost
 249
0
How Mishkā links women’s livelihoods to Cairo’s regeneration
 297
0
How states can crowd in local early-stage capital
254
0
Why last-mile healthcare needs an operating model, not just more mobile clinics
 216
0
How Australia’s succession wave could turn ownership into a funding model
 309
0
 68
0
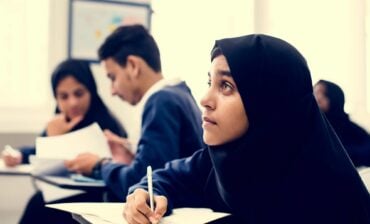
Ethical finance’s promise comes into focus in people’s lives: what they learn, the opportunities they gain, and whether those benefits endure; Photo by Curated Lifestyle
Ethical intentions and sound financial structures cannot, on their own, demonstrate social benefit. Ainurul Rosli and Fara Mohammad examine Sukuk Ihsan, outcomes-based finance, and the case for keeping an outcome ledger alongside compliance — with affected people helping to define success.
A financial product can be Shariah-compliant, aligned with the Sustainable Development Goals, externally reviewed, and governed by credible institutions — and still leave one decisive question unanswered: what changed for the people it was meant to serve?
Shariah compliance addresses whether a product is structured in accordance with Islamic legal and ethical requirements. SDG alignment connects its stated purpose to global sustainability priorities. External reviews and disclosures can provide assurance that proceeds were used as promised. None of these, on its own, establishes whose circumstances improved, whether benefits were fairly distributed, or whether the change lasted.
That is the accountability challenge facing ethical finance. Capital must be deployed responsibly, but the account cannot end with the transaction. It must also examine what people experience as a result.
Malaysia’s Sukuk Ihsan offers a useful starting point. In 2015, Khazanah Nasional launched the financing structure to support Yayasan AMIR’s Trust Schools Programme, which aimed to improve access to quality education in government-funded schools.
The structure went beyond specifying where proceeds would go. It linked investor repayment to program performance over a five-year observation period. Under the 2015 terms, investors would forgo a pre-agreed portion of the principal if the key performance indicators were met. The achievement of these indicators would therefore trigger a pre-agreed investor social contribution to the program through a reduction in the amount repayable at maturity, recognizing the positive social impact generated by the Trust Schools Programme.
Khazanah’s 2017 announcement of a second tranche described indicators covering the number of participating schools, teacher and school-leadership performance, and student outcomes. These indicators are more informative than a record of how much money was allocated to education.
Although the KPIs moved beyond measuring financial inputs alone, they remained focused largely on agreed aspects of program delivery and selected intended educational outcomes. They therefore provided a pathway toward outcome-oriented finance without constituting a complete assessment of long-term educational or social impact. Understanding whether improvements endure, how they are distributed, what students and families value, and how much change the program contributed requires complementary evidence.
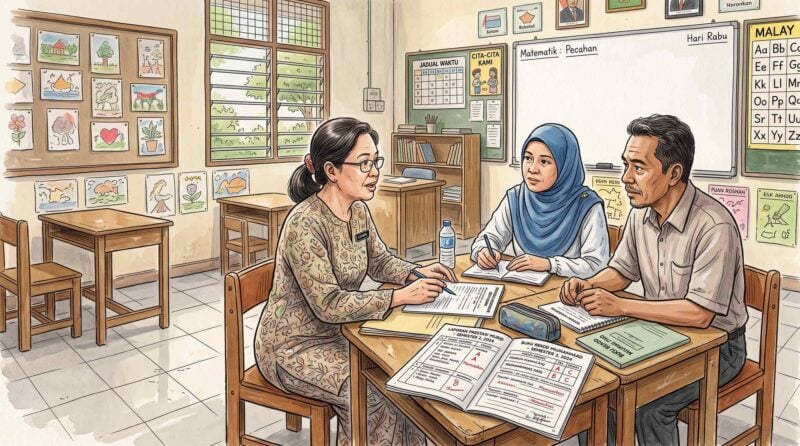
In education finance, tracking delivery is one part of accountability. Understanding lasting changes for students and families requires complementary evidence.
Sukuk Ihsan is an important step toward outcome-oriented finance. Its usefulness also lies in showing why financial KPIs should be part of a broader account of social value.
Impact investing and Islamic finance begin from different intellectual foundations. Both make ethical claims about capital’s contribution to human and social wellbeing.
Impact investing combines the intention to generate positive, measurable social or environmental impact with a financial return. The Global Impact Investing Network estimated worldwide impact-investing assets under management at approximately $1.57 trillion in 2024. The scale of those assets makes the quality of impact claims consequential.
Capital must be deployed responsibly, but the account cannot end with the transaction.
Islamic finance is grounded in an ethical tradition that includes the prohibition of interest, or riba, restrictions on excessive uncertainty and exploitation, and principles concerning risk-sharing and legitimate economic activity. Islamic social finance also draws on zakat and waqf. The wider orientation is toward justice, responsibility, shared prosperity, and human dignity.
In both fields, intentions, structures, and reporting frameworks can be present without sufficient evidence of benefit. Impact-washing describes the risk of presenting impact claims without credible evidence of change. In Islamic finance, a related risk arises when formal compliance is treated as sufficient evidence of wider ethical achievement. This is a question about the claims made for a product, not a dismissal of Shariah governance.
Bank Negara Malaysia’s Value-Based Intermediation initiative seeks to orient Islamic finance toward the intended outcomes of Shariah through institutions’ practices, conduct, and offerings. Its Financing and Investment Impact Assessment Framework supports impact-based assessment of financing and investment activities.
This sits within a wider movement toward values-based banking. The Global Alliance for Banking on Values emphasizes the real economy, social and environmental benefit, long-term relationships, resilience, and transparent, inclusive governance. VBI expresses related concerns through the ethical and institutional language of Islamic finance.
The Malaysian Institute of Accountants and the World Bank have also developed an Industry Guide on Impact Monitoring and Reporting for Islamic Social Finance, launched in June 2026. It offers practical, proportionate guidance connecting impact-management practice with maqasid al-Shariah — the objectives of Islamic law. As a voluntary guide, it provides institutions with a reference point and practical tools for developing ethical commitments into an ongoing discipline of assessment and learning.
The Peterborough Social Impact Bond provides a complementary example. Launched in England in 2010, it financed support for men leaving prison after short sentences. Investor repayment depended on reducing reconviction events. The result reported in 2017 was a reduction of approximately 9% across two cohorts relative to a comparison group, exceeding the contractual threshold of 7.5%.
Peterborough showed that a defined social outcome could be written into a financing contract and affect investor repayment. It did not establish that impact bonds will always outperform conventional public funding. Designing contracts, coordinating services, and measuring outcomes all carry costs. A World Bank review identified limited evaluation evidence for claims of better outcomes compared with typical contracting models, alongside the need to reduce transaction costs.
The distinction matters: evidence that a program achieved its contracted outcome is not the same as evidence that its financing model is the best way to achieve that outcome.
An outcome ledger brings evidence into institutional decisions, asking what changed, for whom, and how institutions should respond; Photo by Curated Lifestyle
The outcome ledger must include unintended consequences and harm. Who lost out? Were some people excluded? Was a negative effect addressed? Recording only the benefits gives an incomplete account, even when those benefits are real.
The Social Value International principles offer a discipline for this work: involve affected stakeholders, understand intended and unintended changes, value what matters to them, include material information, avoid overclaiming, remain transparent, verify results, and respond to the evidence.
These principles turn measurement into a basis for decisions. Listening to people matters not only because it improves a report, but because it can change what an institution funds, how a service operates, or which harms it addresses.
For Islamic impact investment, we suggest four layers of accountability:
| Layer | Question | Practical discipline |
|---|---|---|
| Permissible | Is the activity allowed? | Shariah screening and review of the activities and financing structure. |
| Structured fairly | How are risk, reward, information, and responsibility distributed? | Transparent terms, fair risk allocation, and safeguards for affected stakeholders. |
| Purposeful | What contribution to wellbeing is intended? | A maqasid-informed theory of change and an outcome framework. |
| Provable | What can be evidenced without overclaiming? | Baseline data, stakeholder testimony, proportionate verification, and follow-up. |
Each layer asks something the others cannot settle alone. A permissible activity may still distribute risks unfairly. A compelling purpose may lack evidence. A measured benefit may coexist with harm that the chosen indicators miss.
A credible Islamic impact investment should be permissible, fairly structured, purposeful, and provable.
Maqasid can orient measurement toward justice, wellbeing, dignity, stewardship, and responsibility. We offer the following mapping as a practical interpretation, not a definitive classification or a replacement for engagement with affected people.
| Area of protection | Possible outcome domains |
|---|---|
| Life | Physical and mental health, safety, and environmental quality. |
| Intellect | Education, knowledge, skills, and capability. |
| Wealth | Fair distribution, livelihoods, economic security, and resilience. |
| Lineage and family | Social cohesion, care, inclusion, and community resilience. |
| Faith | Meaning, dignity, agency, purpose, and freedom of conscience. |
Maqasid and the Social Value principles operate at different levels. The former provides an ethical orientation; the latter helps practitioners ask whose outcomes matter, how change is evidenced, and whether the claims match the evidence. Neither removes the need to make judgments in context.
For issuers and financial institutions, maintaining both ledgers means defining intended outcomes before deployment, establishing a baseline, and budgeting for follow-up. Reporting should explain what changed, for whom, over what period, and with what limitations. It should distinguish an investment’s contribution from changes that may have happened anyway.
For Shariah boards and other governance bodies, the opportunity is to consider outcome evidence alongside the review of structure and permissibility, with appropriate impact expertise. When evidence reveals harm or uneven benefits, institutions should have a process for deciding what to change and explaining their response.
For impact investors, Islamic finance offers an invitation to examine fairness in the transaction itself: how risk and reward are shared, what obligations capital creates, and whose interests the structure protects. For both fields, affected people should help define success and have a meaningful role in interpreting the results.
A credible Islamic impact investment should be permissible, fairly structured, purposeful, and provable. Keeping both ledgers would make the ethical claim more demanding — and more useful. The test is whether people experienced meaningful improvement, whether harm was recognized and addressed, and whether the evidence is strong enough for others to scrutinize.
Disclosure: Ainurul Rosli is a Trustee of Social Value International, whose principles this article discusses.
Related Content
After the flood, recovery capital must do more than replace what was lost
249
0
How Mishkā links women’s livelihoods to Cairo’s regeneration
297
0
How a Brampton program builds skills, income, and belonging
 371
0

How displaced Artsakhtsi are rebuilding livelihoods
 301
0
Comments
Deep Dives
RECENT
 254
0
 216
0
 309
0
Editor's Picks
 68
0
 4327
0
 5799
0
68
0
68
0
 249
0
 297
0
Webinars
Signed by the author. Collected at the door at Lipton Hall, NYU School of Law,…
Signed and personally inscribed — you'll write the inscription as you order. Limited · 50…
News & Events
Seeking a new generation of leaders in coastal sustainability
A public-interest foundation keeps 63.3% of the voting rights
A pilot loan program returns the interest to borrowers who repay
Subscribe to our newsletter to receive updates about new Magazine content and upcoming webinars, deep dives, and events.
Become a Premium Member to access the full library of webinars and deep dives, exclusive membership portal, member directory, message board, and curated live chats.

0 Comments